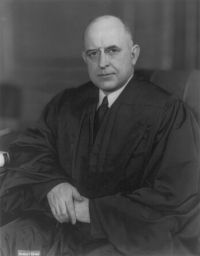
 Stanley Forman Reed,
Braniff Airways v. Nebraska State Board of Equalization and Assessment…
“ It is stipulated that the tax in question is assessed only against regularly scheduled air carriers and is not applied to carriers who operate only intermittently in the state. The statute defines 'flight equipment' as 'aircraft fully equipped for flight', [2] and provides that 'Any tax upon or measured by the value of flight equipment of air carriers incorporated or doing business in this state shall be assessed and collected by the Tax Commissioner.' [3] A formula is prescribed for arriving at the proportion of a carrier's flight equipment to be allocated to the state. ”
