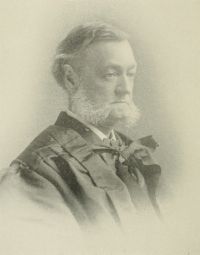
 George Shiras, Jr.,
Caldwell v. North Carolina — Opinion of the Court
“ Transactions between manufacturing companies in one state, through agents, with citizens of another, constitute a large part of interstate commerce; and for us to hold, with the court below, that the same articles, if sent by rail directly to the purchaser, are free from state taxation, but, if sent to an agent to deliver, are taxable through a license tax upon the agent, would evidently take a considerable portion of such traffic out of the salutary protection of the interstate commerce clause of the Constitution. ”
