Summary

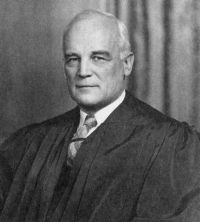
Portrait of Harold Hitz Burton Harold Hitz Burton Spiegel's Estate v. Commissioner of Internal Revenue…

Passage of time will soon eliminate transfers made prior to that date by settlors who are yet to die or who have died and whose estates may still be forced to include such transfers for federal estate tax purposes. The 1931 legislation plus the passage of time would thus have disposed of May v. Heiner without the injustices that will now arise from its reversal.
Value is added to the fully considered decisions of this Court by our own respect for them. Faith is justifiable that this Court will exercise extreme self-restraint in using its power of self-reversal.
Source: Wikisource

Portrait of Harold Hitz Burton Harold Hitz Burton Spiegel's Estate v. Commissioner of Internal Revenue…

While that power is essential in appropriate cases and is an inherent part of this Court's finality of jurisdiction, each case that suggests its use should be scrutinized with the utmost care. In the instant case I find arguments to suggest and support, but not to require, a construction of the statute contrary to that originally given in May v. Heiner. I find nothing sufficient to justify the reversal of this Court's original construction 18 years after this Court approved it unanimously and 17 years after this Court unanimously reaffirmed that approval.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature