Summary

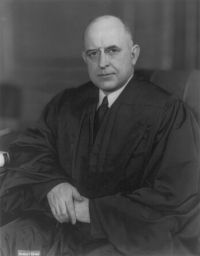
Portrait of Stanley Forman Reed Stanley Forman Reed Spiegel's Estate v. Commissioner of Internal Revenue…

On that basis it is now decided that if there is a possibility, due to the terms of the instrument or by operation of law, however remote, that settled property may return to the settlor, the entire trust property must be included in the gross estate for purposes of the federal estate tax. Thus, under the Court's decision tax liability may be incurred by the discovery of a gossamer thread of possession or enjoyment, which has no value. Nevertheless the entire trust corpus is included in the gross estate and taxed as if the settlor really had possession or enjoyment of the property.
Source: Wikisource

Portrait of Stanley Forman Reed Stanley Forman Reed Spiegel's Estate v. Commissioner of Internal Revenue…

Granting that in early interpretations of the sections this Court might logically have determined that remote possibilities of reverter did not interfere with the beneficiaries' complete possession and enjoyment of the gift during the lifetime of the donor, the balance of experience and precedent, since Helvering v. Hallock, tips the scale the other way in my judgment. It is important, though not decisive, since we are not justified in pushing every rule to its logical extreme, that this conclusion is a logical outgrowth of the Hallock rule.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature