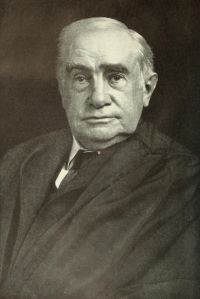
 Henry Billings Brown,
American Sugar Refining Company v…
“ The Constitution of Louisiana classifies the refiners of sugar for the purpose of taxation into those who refine the products of their own plantations, and those who engage in a general refining business, and refine sugars purchased by themselves or put in their hands by others for that purpose, imposing a tax only upon the latter class. To entitle a party to the exemption it must appear (1) that he is a farmer or a planter; (2) that he grinds the cane as well as refines the sugar and molasses; (3) that he refines his own sugar and molasses, meaning thereby the product of his own plantation. ”
