License tax

Definition and stakes

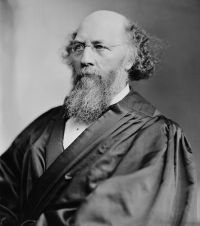
Portrait of Stephen Johnson Field Stephen Johnson Field Welton v. Missouri — Opinion of the Court

Where the business or occupation consists in the sale of goods, the license tax required for its pursuit is in effect a tax upon the goods themselves. If such a tax be within the power of the State to levy, it matters not whether it be raised directly from the goods, or indirectly from them through the license to the sealer; but, if such tax conflict with any power vested in Congress by the Constitution of the United States, it will not be any the less invalid because enforced through the form of a personal license.
Source: Wikisource

Portrait of William R. Day William R. Day City of St. Louis v. United Railways Company…

In the fixing of a license tax upon all companies alike for the privilege of using cars in the city, it is exerting other charter powers. It makes provision uniformly applicable to all persons or companies using street cars. It is a revenue measure equally applicable to all coming within its terms. We do not perceive that the exercise of the power to grant privileges in the streets in making terms with companies seeking such rights, in the absence of plain and unequivocal terms to that effect, excludes the city's right to impose the license tax under the power conferred for that purpose.
Source: Wikisource

Owen J. Roberts Caskey Baking Company v. Virginia…

Wholesale merchants who have a fixed place of business pay a license tax measured by a percentage of all their purchases; and if they are also licensed by the town or city in which they have their place of business or, in lieu thereof, are taxed by such town or city on the capital employed in the business, they may sell and deliver at the same time and place anywhere in the State without payment of any additional license tax.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature