Summary

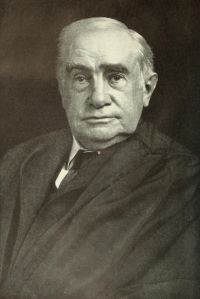
Portrait of Henry Billings Brown Henry Billings Brown Hodge v. Muscatine County — Opinion of the Court

It is not easy to draw an exact line of demarcation between a tax and a penalty, but, in view of the fact that the statute denominates the assessment a 'tax,' and provides proceedings appropriate for the collection of a tax, but not for the enforcement of a penalty, and does not contemplate a criminal prosecution, we cannot go far afield in treating it as a tax rather than a penalty.
Source: Wikisource

Portrait of Henry Billings Brown Henry Billings Brown Hodge v. Muscatine County — Opinion of the Court

By § 5007, printed in full in the Marshall County Case, a tax of $300 per annum is assessed 'against every person . . . and upon the real property and the owner thereof,' whereon cigarettes, etc., are sold, or kept with intent to be sold, with a provision that 'such tax shall be in addition to all other taxes and penalties, shall be assessed, collected, and distributed in the same manner as the mulct liquor tax, and shall be a perpetual lien upon all property, both personal and real, used in connection with the business
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature