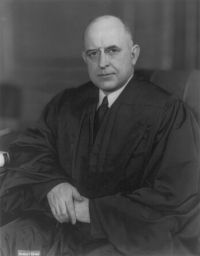
 Stanley Forman Reed,
Moline Properties v. Commissioner of Internal Revenue…
“ Petitioner advances what we think is basically the same argument of identity in a different form. It urges that it is a mere agent for its sole stockholder and 'therefore the same tax consequences follow as in the case of any corporate agent or fiduciary.' There was no actual contract of agency, nor the usual incidents of an agency relationship. Surely the mere fact of the existence of a corporation with one or several stockholders, regardless of the corporation's business activities, does not make the corporation the agent of its stockholders. ”
