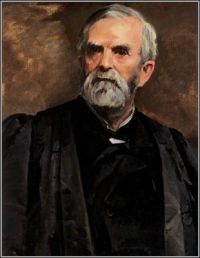
 William Burnham Woods,
Kings Company Savings Institution v…
“ We regard the presentation of the claims to the commissioner of internal revenue for the refunding of a tax alleged to have been illegally exacted as a condition on which alone the government consents to litigate the lawfulness of the original tax. It is clearly not the intent of the statute to allown the collector to be sued unless the tax-payer has first applied for relief to the commissioner within the time and in the manner pointed out by law, and relief has been denied him. ”
