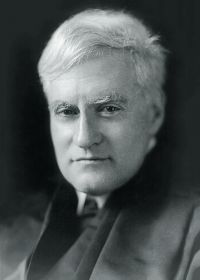
 Benjamin N. Cardozo,
Lee v. Bickell — Opinion of the Court
“ One finds it hard, indeed, to see how the collection of the tax would be workable as an administrative problem if a broker were free to choose between stamping his own copy of a document and stamping the duplicate delivered as a memorandum to his customer. The taxing officials could never learn through an inspection of the files whether the mandate of the statute had been followed or ignored. One of the major merits of a stamp tax is to make the evidence of payment visible and almost automatic. ”
