Summary

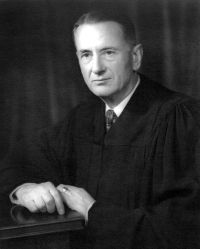
Portrait of Charles Evans Whittaker Charles Evans Whittaker United States v. Consolidated Edison Company of New York…

Of course, an unconditional 'payment' made by a taxpayer in apparent 'satisfaction' of an asserted matured tax liability is, without more, plain and persuasive evidence, at least against the taxpayer, that 'all the events (have) occur (red) which fix the amount of the tax and determine the liability of the taxpayer to pay it,' United States v. Anderson, supra, 269 U.S. at page 441, 46 S.Ct. at page 134, and that the item so paid and satisfied has accrued.
Source: Wikisource

Portrait of Charles Evans Whittaker Charles Evans Whittaker United States v. Consolidated Edison Company of New York…

And after pointing to this Court's use of the phrase 'and failed to pay' in its holding in the Security Flour Mills case that 'Since (the taxpayer) denied liability for, and failed to pay, the tax during the taxable year 1935, it was not in a position in its tax accounting to treat the Government's claim as an accrued liability,' the Court of Claims concluded: 'In the instant case the taxpayer denied liability, but paid. We think it thereby 'accrued' the taxes and interest, if accrual is requisite at all, in the case of the debtor, when actual payment has occurred.' 62 F.Supp.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature