Summary

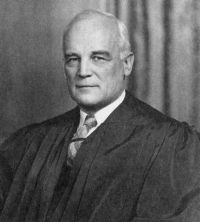
Portrait of Harold Hitz Burton Harold Hitz Burton United States v. Benedict (338 U.S. 692…

But the fact that a taxpayer may astutely apply his income so as to reduce the net base on which a tax is to be levied is not in itself ground for rejecting a construction of the Revenue Code which permits the reduced base, even though the particular mode of distributing his income may not have been contemplated in the enactment of the classes of exemptions and deductions within which the taxpayer brings himself.
Source: Wikisource

Portrait of Harold Hitz Burton Harold Hitz Burton United States v. Benedict (338 U.S. 692…

A deduction for trust income applied to charitable purposes should not be disallowed merely because one taxpayer can effect the payment of a lower income tax than another through the mode by which the charitable contribution is made. Thus, where the trust instrument provides that all charitable donations shall be allocated from ordinary income and not from capital gains, the taxpayer may doubtless deduct such charitable contributions in full and may at the same time report any capital gains under the special capital gains provisions of the Code.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature