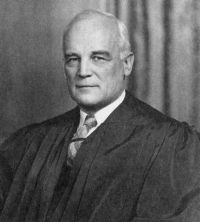
 Harold Hitz Burton,
Watson v. Commissioner of Internal Revenue…
“ Whether or not the crop be real property, the federal income tax upon the gain resulting from its sale is, in its nature, a subject of federal law.The Commissioner urges two grounds in support of his position that § 117 (j) does not authorize the taxpayer's treatment of the proceeds of the unmatured crop as a capital gain. The first is that the proceeds fairly attributable to the crop are derived from property held by the taxpayer primarily for sale to customers in the ordinary course of the taxpayer's trade or business. ”
