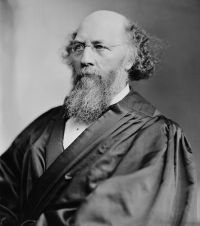
 Stephen Johnson Field,
Gray v. Darlington — Opinion of the Court
“ The mere fact that property has advanced in value between the date of its acquisition and sale does not authorize the imposition of the tax on the amount of the advance. Mere advance in value in no sense constitutes the gains, profits, or income specified by the statute. ”
