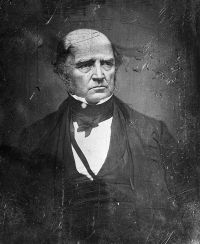
 Levi Woodbury,
Greely v. Thompson — Opinion of the Court
“ Indeed, it would seem reasonable, independent of the express language of the acts of Congress, that, if uncertainty remained about the true construction of the fifth section of the act of 1823, the proper time for fixing the value of goods should be considered the time they were purchased or procured; because the idea of having the value and charges fixed, and assessing the duty on them, is to tax the importer on the amount or value he has expended. And what he has expended cannot be more than what he has thus paid ”
