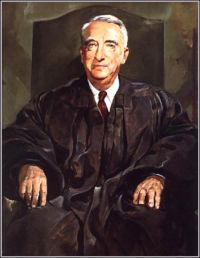
 Fred M. Vinson,
Commissioner of Internal Revenue v…
“ Congress, and the Treasury in advising Congress, may well have concluded that the best manner of affording him relief and correcting the inequitable treatment of bondholders whose interest receipts were taxable, was to define the scope of the amendment by reference to types of bonds rather than causes of premium payment.As 'bond premium' is used by accountants and other writers in the securities field, it is any payment in addition to face value. ”
