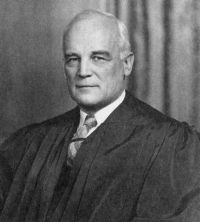
 Harold Hitz Burton,
United States v. Calamaro — Dissent
“ The language of § 3290 does not limit the occupational tax to persons 'accepting wagers' in a contractual sense. Instead, it imposes the tax on 'each person * * * who is engaged in receiving wagers for or on behalf of any person so liable (for the excise tax) .' Those words readily include a pickup man for he is engaged in receiving for the banker the slips which provide the banker with the sole evidence of the wagers made. ”
