Occupational tax

Definition and stakes

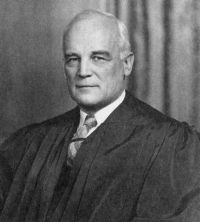
Portrait of Harold Hitz Burton Harold Hitz Burton,  United States v. Calamaro — Dissent

“ The language of § 3290 does not limit the occupational tax to persons 'accepting wagers' in a contractual sense. Instead, it imposes the tax on 'each person * * * who is engaged in receiving wagers for or on behalf of any person so liable (for the excise tax) .' Those words readily include a pickup man for he is engaged in receiving for the banker the slips which provide the banker with the sole evidence of the wagers made. ”
Source: Wikisource

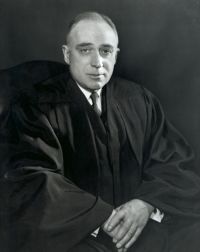
Portrait of John Marshall Harlan II John Marshall Harlan II,  United States v. Calamaro — Opinion of the Court

“ Thus, while Example 2 of that regulation purports to make the pick-up man liable for the § 3290 occupational tax, Example 1 of the same regulation provides that 'a secretary and bookkeeper' of one 'engaged in the business of accepting horse race bets' are not liable for the occupational tax 'unless they also receive wagers' for the person so engaged in business, although those who 'receive wagers by telephone' are so liable. ”
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature