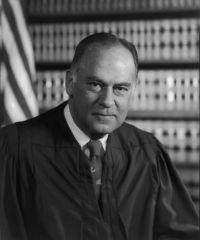
 Potter Stewart,
United States v. Correll — Opinion of the Court
“ As a result, even the taxpayer who incurs substantial hotel and restaurant expenses because of the special demands of business travel receives something of a windfall, for at least part of what he spends on meals represents a personal living expense that other taxpayers must bear without receiving any deduction at all. ”
