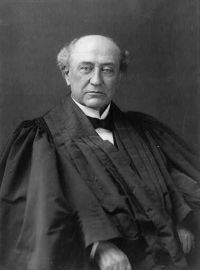
 David Josiah Brewer,
New York ex rel. Metropolitan Street Railway Company v…
“ It would not be doubted that, if a grant was of specific tangible property, like a tract of land, and the payment therefor was a gross sum, no implication of an exemption from taxation would arise. Whether the amount paid was large or small, greater or less than the real value, if the payment was distinctly the consideration of a grant, that which was granted would pass into the bulk of private property, and, like all other such property, be subject to taxation. ”
