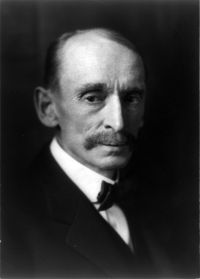
 William R. Day,
Maxwell v. Bugbee Hill — Opinion of the Court
“ It is not to be disputed that, consistently with the federal Constitution, a state may not tax property beyond its territorial jurisdiction; but the subject-matter here regulated is a privilege to succeed to property which is within the jurisdiction of the state. When the state levies taxes within its authority, property not in itself taxable by the state may be used as a measure of the tax imposed. ”
