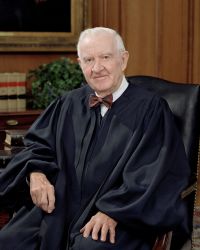
 John Paul Stevens,
United States v. Dalm — Dissenting Opinion
“ The second fact is this: an affluent taxpayer, but not a less fortunate one, can pay a deficiency assessment and file suit for a refund. It is undisputed that if respondent had the means to do so, she could have recovered the gift tax that had been paid in 1976 by a refund action filed after she received the notice of income tax deficiency in 1983, even though the statute of limitations had long since run. One might infer from the posture of this case-as respondent's counsel represented to the Court-that respondent's limited means foreclosed this avenue of relief for her. ”
