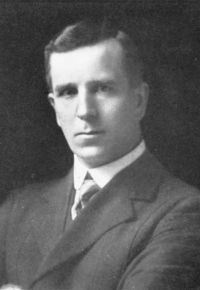
Roy B. Kester, Accounting theory and practice… (1922)
“ While it is true that a great deal of valuable information can be secured from a comparative balance sheet, and that this form of balance sheet locates definitely the changes in the asset and liability items, summarizes those changes, and shows the net profit, it nevertheless fails to disclose the forces within the business organization which have brought about the changes—it sets forth effect or result but not cause. ”