AI-generated from sources
The Stewardship of Wealth, From Personal Virtue to Delegated Trust
In Brief
- Historically, personal financial management was a moral imperative, reflecting virtues such as prudence, honesty, and self-reliance.
- The growing complexity of economic systems necessitated the delegation of financial stewardship to specialized experts and institutions.
- Delegating financial trust introduces significant ethical challenges, including conflicts of interest and the potential for systemic exploitation.
- Navigating modern finance requires a continuous effort to reconcile individual responsibility with rigorous accountability for professional advisors and formal agreements within families.
Main authors

The management of personal finances has long been framed as a reflection of individual character, a domain where virtues such as diligence, frugality, and foresight are paramount. Historically, a strong societal expectation held that individuals should maintain direct stewardship over their own money, a practice seen not merely as a practical skill but as a moral obligation. The right use of money was believed to be intimately connected to honesty, justice, and self-sacrifice, making financial acumen a key test of practical wisdom [6]. This perspective emphasized that prosperity stemmed not from the sheer amount of income, but from a disciplined and systematic relationship between earnings and expenditures [7]. Within this framework, financial independence was the ultimate goal, achieved through careful planning, punctuality in dealings, and a strong sense of self-reliance that viewed dependence on external aid as a last resort [3, 8].
Over time, however, the growing complexity of economic systems began to challenge this ideal of solitary financial stewardship. As markets, investment vehicles, and credit instruments became more sophisticated, the figure of the financial expert emerged as a necessary intermediary. This shift marked a fundamental transition from direct personal control to a model of delegated responsibility, where individuals and corporations increasingly placed their trust in the specialized knowledge of bankers, advisors, and professional managers [9]. While this delegation offered efficiency and access to expertise, it also introduced a new set of ethical ambiguities. The act of entrusting one's wealth to others raised profound questions about accountability, transparency, and the potential for conflicts of interest, creating a persistent tension between the traditional virtue of self-management and the modern reality of professional financial guidance [16, 20].
The Moral Imperative of Financial Self-Management
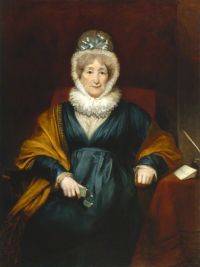
In earlier conceptions of economic life, the handling of money was inseparable from personal ethics. Samuel Smiles argued that a person's ability to make, save, and spend money served as one of the most reliable indicators of their practical wisdom and moral fiber . This was not about the pursuit of wealth as an end in itself, but about the qualities that responsible financial conduct was thought to cultivate. For thinkers like Ralph Waldo Emerson, success was a matter of systematic living, where disciplined spending habits were more critical than the size of one's income . The belief was that true financial well-being originated from an internal sense of order and control, rather than from external circumstances. Even acts of charity were viewed through this lens, with reformers like Hannah More suggesting that the most valuable assistance one could offer the less fortunate was not money itself, but instruction in better economic management [1].
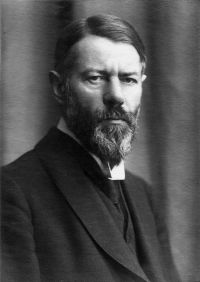
This ethos of self-reliance was supported by a set of practical virtues that were widely promoted as the cornerstones of a respectable life. The development of a budget was considered an essential tool to prevent casual spending from becoming a costly habit [2]. Max Weber, analyzing the work ethic of an earlier era, highlighted punctuality in repaying debts as a key to building a reputation that could unlock further financial opportunities, framing it as a matter of both prudence and justice . The ideal was the individual who, through constant effort and planning, navigated the unpredictable fluctuations of fortune, taking direct responsibility for their financial destiny [4]. The core principle was that one's financial life should remain uncomplicated by the risks and uncertainties of others' ventures, demanding absolute personal control over one's own resources [5].
Ultimately, this philosophy championed financial independence as a crucial component of dignity and self-respect. The prevailing view held that relying on institutional support, such as public poor funds, was incompatible with the honor of an honest worker, who was expected to exhaust every possibility of earning their own subsistence first . The management of money was thus a deeply personal and often arduous journey, a constant effort to balance income and expenses that defined the lived experience of many . This direct engagement with one's own finances was considered not just a private responsibility but a societal good, fostering a populace that was prudent, self-sufficient, and capable of weathering economic hardship through its own disciplined efforts.
The Inevitable Rise of the Financial Expert
As the scale of commerce and industry expanded, the ideal of complete financial self-sufficiency became increasingly untenable, particularly for large organizations. The immense capital required for endeavors like building railroads necessitated a new level of financial sophistication that went beyond the capabilities of operational managers. Howard Elliott argued in 1913 that for such complex needs, the expert advice and aid of bankers were essential, as they possessed the specialized knowledge of where and how to secure necessary funds, freeing company officers to focus on management and public service . This logic extended into the corporate hierarchy itself, where supervision by experienced executives was seen not as a slight against a manager's ability, but as a vital resource for ensuring sound financial housekeeping and operational efficiency [10].
This trend toward professional management soon permeated personal finance as well. For ordinary families, foresight meant entrusting their savings to institutions like banks and insurance companies, which pooled resources to provide for future needs like retirement [11]. This reliance on third parties became a cornerstone of modern financial planning. When making significant decisions, such as purchasing an insurance policy, it became standard practice to seek out what was hoped to be unprejudiced advice from professionals who could navigate the complexities of different financial products [12]. The banker, in particular, assumed a position of great responsibility, expected to act as a judicious and impartial steward of millions of dollars of other people's money, making decisions based on rigorous analysis rather than personal feelings [14].
The entire system of delegated finance rested on a foundation of trust. The sheer volume of money handled daily by clerks, agents, and brokers with relatively few instances of theft or fraud was seen by observers like Samuel Smiles as a testament to the general honesty of society [13]. This perception of integrity was crucial for the system's legitimacy. Figures like Otto H. Kahn actively worked to counter public suspicion, asserting that the leaders of finance were, by necessity, as honorable and patriotic as those in any other profession [15]. The delegation of financial responsibility was thus presented not as an abandonment of personal duty, but as a rational and necessary adaptation to a more complex economic world, one in which expertise was indispensable and trustworthiness was assumed.
The Ethical Perils of Delegated Trust
The delegation of financial responsibility, while practical, created inherent ethical vulnerabilities, chief among them the conflict between an advisor's self-interest and their client's well-being. This problem has been starkly identified in modern times, with figures like Barack Obama pointing out that some retirement advisors could be influenced by backdoor payments to recommend investment products that benefited the advisor more than the client . This misalignment of incentives could cost families tens of thousands of dollars in lost savings, prompting calls for updated regulations that would legally require all retirement advisers to act in their clients' best interests [17]. This issue exposes the core danger of delegation: the trust placed in an expert can be exploited for personal gain.
Historical critics have long warned of the systemic nature of such exploitation. At the turn of the 20th century, writers like Thomas William Lawson and George Graham Rice sought to reveal how the financial system was, in their view, a rigged game designed to enrich insiders [18]. They argued that the savings of ordinary people, held in seemingly safe institutions, were being manipulated in a high-stakes system that funneled wealth to a select few . Decades earlier, Émile Zola had written about a financial world where incapacity and fraud were commonplace, suggesting that the rhetoric of moral superiority in finance was a hollow pretense [22]. These critiques portray a system where the delegation of trust was not just occasionally abused by individuals, but was foundational to a structure of systemic inequality.
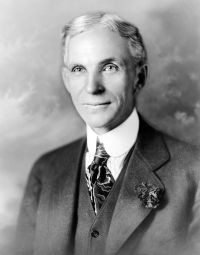
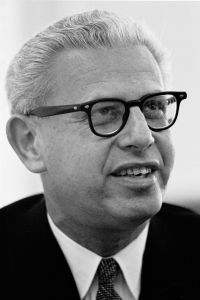
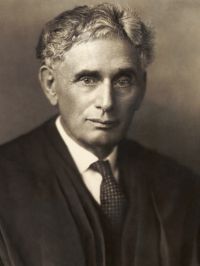
In response to these perceived abuses, reformers have consistently called for greater transparency and structural change. Louis Brandeis argued forcefully against the concentration of power in a "financial oligarchy," advocating for laws to prohibit interlocking directorates, where the same individuals control multiple, supposedly independent, corporations [23]. Henry Ford expressed a similar sentiment, challenging financiers to prioritize the health of the economic system over their own short-term profits [19]. This push for reform extended into the legal sphere, where courts began to establish higher standards of morality for the securities industry. As Justice Arthur Goldberg articulated, the law does not permit an investment adviser to profit from the market effect of their own advice without first fully disclosing their personal interests to their clients, establishing a clear fiduciary duty [21].
Navigating Finance Within the Intimate Sphere of Family
Within the family unit, the dynamic between personal stewardship and delegated management takes on a distinct character, often reflecting evolving social norms. The traditional arrangement, where a husband controlled all household finances, has gradually given way to models of shared or delegated responsibility. As Walter Lionel George observed, a growing tendency for men to provide their wives with a formal allowance and a separate banking account marked a significant shift [24]. This delegation was not merely practical; it was a recognition of the wife's competence, which in turn fostered greater capability. Though some men remained resistant to ceding this control, the idea of a wife managing household expenditures with a trusted allowance was increasingly seen as beneficial for the entire family's financial health [25]. In some cultural settings, this delegation was even the norm, with the wife acting as the family's primary treasurer [28].
Intergenerational financial arrangements present another complex form of delegation. While parents might offer financial support to their adult children for major life events, this help is often distinguished from charity and viewed as part of an ongoing familial relationship [30]. However, this support is bounded by prudence. A. R. Calhoun strongly cautioned elderly parents against deeding their property to their children in exchange for future care, advising instead that any significant financial assistance be formally recorded and treated as an advance on an inheritance to ensure fairness among heirs and protect the parents' security [27]. This reflects a tension between familial trust and the need for formal agreements to prevent potential exploitation and misunderstanding.
Formal legal instruments like trusts represent the most structured form of delegated financial management within a family. As described in a Supreme Court opinion by William O. Douglas, a trust can serve as a "temporary reallocation of income within an intimate family group," often allowing the creator of the trust to retain significant control over the assets while distributing the income to family members [26]. Such arrangements can be designed to provide for multiple generations, as seen in the trust established by Mary Baker Eddy, which guaranteed income for her son and his wife and provided for the education and inheritance of her grandchildren under the management of appointed trustees [29]. These mechanisms formalize the delegation of financial stewardship, replacing informal understandings with legally binding duties to manage wealth on behalf of others.
The historical narrative of personal finance reveals a profound and enduring tension between two competing ideals. On one hand lies the deeply ingrained ethic of individual stewardship, where the direct management of one's own money is seen as a crucible of character, a measure of prudence, honesty, and self-reliance . This view posits financial autonomy not just as a practical goal but as a moral imperative, essential for personal dignity and social stability . On the other hand, the inexorable rise of economic complexity has made the delegation of financial responsibility to professional experts a practical necessity for both corporations and individuals . This shift created a new paradigm based on trust in outside expertise, but it also opened the door to ethical failings, from conflicts of interest to systemic manipulation, that have been a recurring source of public anxiety and critique .
Ultimately, the discourse is not merely a choice between self-management and delegation, but a continuous effort to reconcile trust with accountability. The challenge for modern society is to construct and regulate a system of financial expertise that is both effective and ethically sound. The principles of fiduciary duty, transparency, and the alignment of interests must be rigorously applied to ensure that those who are entrusted with others' money prioritize their clients' welfare above all else . This imperative extends from the sprawling public marketplace to the most intimate financial arrangements within a family, reminding us that whether stewardship is personal or delegated, its legitimacy always depends on the integrity with which it is exercised.