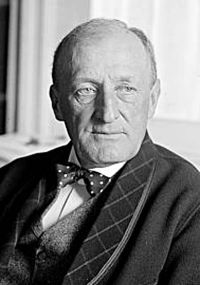
 James Clark McReynolds,
Helvering v. Falk — Opinion of the Court
“ The function of the allowance for depletion as a means of securing to the taxpayer a credit against gross income for so much of his capital investment as is restored from the income does not differ from that for depreciation or obsolescence when allowed as a deduction. ”