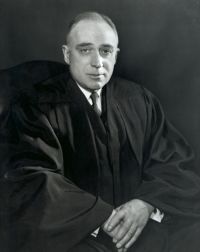
 John Marshall Harlan II,
Flemming v. Nestor — Opinion of the Court
“ Of special importance in this case is the fact that eligibility for benefits, and the amount of such benefits, do not in any true sense depend on contribution to the program through the payment of taxes, but rather on the earnings record of the primary beneficiary.The program is financed through a payroll tax levied on employees in covered employment, and on their employers. The tax rate, which is a fixed percentage of the first $4,800 of employee annual income, is set at a scale which will increase from year to year, presumably to keep pace with rising benefit costs. ”